Reliance Industries is India's largest listed company by revenue and market capitalisation, built around five genuinely distinct businesses under one share: Oil-to-Chemicals (O2C, refining and petrochemicals), Oil & Gas exploration, Digital Services (Jio Platforms, 66.43%-owned), Retail (Reliance Retail Ventures, 83.56%-owned), and a fifth, not-yet-monetised New Energy business building India's largest clean-energy manufacturing complex at Jamnagar. Consolidated Q1 FY27 (quarter to June 2026) revenue reached ₹340,257 crore (+24.5% YoY) and EBITDA ₹54,067 crore (+10.1% YoY), both beating every brokerage preview we found, with O2C, Jio and Retail all contributing to the beat.
The stock has not followed the earnings. RIL closed at a 17-month low on 24 September 2026 — five days before this report's research was compiled — despite roughly 30 of 31 tracked analysts rating it Buy and a consensus target implying 26-41% upside from current levels (sources vary). That disconnect is the report's starting puzzle, and a segment-by-segment Sum-of-the-Parts valuation is the natural tool for solving it: RIL's own consolidated P&L does not yet show what Jio Platforms and Reliance Retail are actually worth, because both carry externally-held minority stakes from 2020-era private placements, and because the single biggest re-rating catalyst — a SEBI-cleared Jio Platforms IPO, filed and approved for listing in August 2026 — has not happened yet.
Our own SOTP, built bottom-up from disclosed segment EBITDA, sourced brokerage valuation marks for the unlisted Jio Platforms and Reliance Retail businesses, and RIL's own reported net debt, lands at a base case of ₹1,609 per share (+36.1% from CMP) — comfortably inside the range independently reached by Street brokerages (₹1,510-1,870) despite being built from first principles rather than copied from any single note. Even our bear case, which assigns zero value to the entirely-undisclosed New Energy segment and applies conservative multiples throughout, still clears the current price by a small margin.
Net: BUY. The case does not require New Energy to succeed, does not require the Jio IPO to price at the top of its sourced range, and does not require the conglomerate discount to close — it only requires that Jio Platforms and Reliance Retail are worth something close to what informed private investors and the company's own IPO process have already priced them at, which the current share price does not yet reflect.
RIL is a mainboard NSE/BSE-listed company (also GDR-listed in London) subject to the full SEBI LODR regime (Regulations 17-27), including enhanced related-party-transaction disclosure appropriate to a company of its index weight (a core NIFTY 50/SENSEX constituent). Its O2C and Oil & Gas businesses carry additional sector regulation (PNGRB, MoPNG); Jio Platforms' pending IPO brings it under SEBI's ICDR (issue) regime on top of LODR; Jio Financial Services, though a separately listed entity following its 2023 demerger, shares the same ultimate promoter group and therefore the same related-party-scrutiny logic applies across the two listed entities.
RIL has continued paying a dividend (₹6.00/share for FY26) despite an active, multi-segment capex programme, and has proactively sought (and received) two investment-grade rating upgrades in six months — a process that requires sustained financial transparency to the rating agencies, not just to public markets. The Jio Platforms IPO structure is a genuinely shareholder-friendly design choice: it is a 100% fresh issue with no promoter offer-for-sale, and disclosed proceeds are earmarked mainly for repaying ~₹27,500 crore of Reliance Jio Infocomm's own borrowings rather than for promoter liquidity. Promoter shareholding has been rising, not falling, over the past several quarters — the opposite direction from what a reader should worry about.
A related-party arrangement between Jio Financial Services' leasing subsidiary and Reliance Retail (a large router-leasing deal, cited in one secondary source at a scale of "$4.4 billion" but not independently corroborated in our own research) sits between two promoter-group-linked entities and deserves a named mention even though we could not verify its exact terms. Anant Ambani's appointment as an Executive Director of RIL (five-year term from 1 May 2025) was approved by a narrower shareholder margin (92.75%) than earlier board inductions for his siblings (98%) — not a red flag on its own, but a data point worth tracking as succession dynamics at a company this size continue to play out. More broadly, the web of related entities across RIL, Jio Platforms' external minority investors, Jio Financial Services, and the JioStar media joint venture is genuinely complex, and a reader should not assume full visibility into every inter-company economic arrangement from public disclosure alone.
Two, both disclosed and dated, neither disqualifying at this scale. On 2 December 2025, the Supreme Court upheld a ₹30 lakh SEBI penalty against RIL and two senior compliance officers for delayed disclosure of the 2020 Facebook-Jio Platforms investment — RIL's formal announcement followed roughly a month after the Financial Times had already reported the near-deal. On 6 July 2026, SEBI issued RIL an administrative warning (not a financial penalty) over share dealing by two employees and one employee's family member who allegedly held unpublished price-sensitive information in July 2024; RIL has stated it will address SEBI's concerns. Neither matter is a structural governance failure, but per this report's own standards, both are named explicitly rather than treated as immaterial simply because RIL is large.
The Jio Platforms IPO's final listing date, issue price and post-listing market performance — the nearest-term governance-and-valuation-relevant event in this entire report. Any further disclosure on the JFS-Reliance Retail related-party leasing arrangement. Independent confirmation of RIL's exact residual equity stake (if any) in Jio Financial Services, which our own research could not verify with a dated primary source and which we have therefore treated as nil for SOTP purposes (see §8).
Adequate, with two disclosed matters that argue for care rather than alarm. Neither the FY2020 delayed-disclosure penalty nor the 2026 employee-trading warning rises to a structural failure, and RIL's own behaviour — continued dividends, rating-agency transparency, a no-OFS IPO structure — supports reasonable trust. But the sheer complexity of the RIL/Jio-minority-investor/JFS/JioStar web means a reader should not assume complete visibility into every related-party economic flow. That complexity belongs in the width of this report's SOTP range, not in a footnote — which is exactly how it has been used here.
RIL is exactly the kind of company a single consolidated P/E cannot value well: two of its five businesses (Jio Platforms, Reliance Retail) carry large external minority stakes from 2020-era private placements and are not separately listed, one (New Energy) discloses no P&L at all, and the whole is run as five genuinely different businesses rather than one operating model. We build enterprise value segment by segment, apply RIL's actual disclosed ownership percentage in each, sum the parts, then bridge to equity value using RIL's own reported net debt.
| Segment | Basis | 100% EV — Bear | 100% EV — Base | 100% EV — Bull | RIL stake |
|---|---|---|---|---|---|
| O2C (refining+chemicals) | 6.5x/7.5x/8.5x FY26 EBITDA (₹60,546cr)* | 3,93,549 | 4,54,095 | 5,14,641 | 100% |
| Oil & Gas (E&P) | 4.0x/4.5x/5.0x FY26 EBITDA (₹19,050cr)* | 76,200 | 85,725 | 95,250 | 100% |
| Jio Platforms | Sourced EV: $100bn/$120bn/$144bn† @ ₹88/US$ | 8,80,000 | 10,56,000 | 12,67,200 | 66.43% |
| Reliance Retail Ventures | Sourced EV: $90bn/$121bn/$140bn‡ @ ₹88/US$ | 7,92,000 | 10,64,800 | 12,32,000 | 83.56% |
| New Energy | ₹0 / Equirus 1.5x invested capital / indicative uplift§ | 0 | 1,20,000 | 1,80,000 | 100% |
| JioStar (media JV) | Nov-2024 deal value $8.5bn / indicative uplift¶ | 74,800 | 74,800 | 88,000 | 63.16%** |
| RIL-attributable enterprise value (sum of stakes above) | |||||
| 17,63,572 | 22,98,327 | 27,16,992 | |||
| Less: net debt (30 Jun 2026, primary source) | (1,22,914) | (1,22,914) | (1,22,914) | ||
| Equity value attributable to RIL shareholders | 16,40,658 | 21,75,413 | 25,94,078 | ||
| ÷ Shares outstanding (derived, mcap÷CMP)ⓘ | 1,352.2cr | 1,352.2cr | 1,352.2cr | ||
| SOTP value per share | ₹1,214 | ₹1,609 | ₹1,918 | ||
| Upside/(downside) vs CMP ₹1,182 | +2.7% | +36.1% | +62.3% | ||
*No O2C- or E&P-specific EV/EBITDA multiple was found stated by any brokerage; the range used is an indicative construction cross-checked against RIL's own blended forward EV/EBITDA of ~9.6-9.9x (Equirus Securities, 11 Jun 2026) and is explicitly conservative for O2C given its lower growth versus Jio/Retail. †Jio Platforms EV sources: $100bn (SEBI-cleared IPO valuation reportedly in focus, Aug 2026), $120bn (mid-point of an unverified post-AGM brokerage range of $117-127bn, Jun 2026), $144bn (Jefferies, 13 Mar 2026, explicitly 13x FY28E EBITDA). Sourced range spans $92bn (JPMorgan, ~Sep 2025) to $190bn (CLSA's 2028 forward estimate) — see Notes for why these were not simply averaged. ‡Reliance Retail EV sources: $90bn (indicative discount to the stale Oct-2023 $100bn mark, reflecting a recent, Q1 FY27 EBITDA-margin compression of 80bps YoY), $121bn (JPMorgan, ~Sep 2025, methodology not disclosed), $140bn (indicative bull case). §New Energy: JPMorgan and CLSA both explicitly assign zero value today (our bear case); Equirus Securities' ₹1,20,000cr base case uses a 1.5x-invested-capital approach, not an EBITDA multiple, because no P&L is disclosed; our bull case is an indicative uplift, not brokerage-sourced. ¶JioStar: $8.5bn is the Nov-2024 deal-completion value; no 2025-26 update was found, so bear=base; bull is an indicative uplift reflecting FY26 EBITDA growth ("sharp turnaround" per Exchange4Media). **RIL's own 16.34% direct stake plus its 46.82% economic interest via Viacom18. ⓘWikipedia cites ~644.51cr shares outstanding, undated; this does not reconcile with mcap÷CMP (~1,352cr) as of the 29 Sep 2026 snapshot used throughout this report, most likely reflecting a stale pre-2024 count before RIL's 1:1 bonus share issue — we use the derived, internally-consistent 1,352.2cr figure rather than the stale one. FX assumed at ₹88/US$, stated explicitly since none of the underlying dollar-denominated sources specify their own conversion rate.
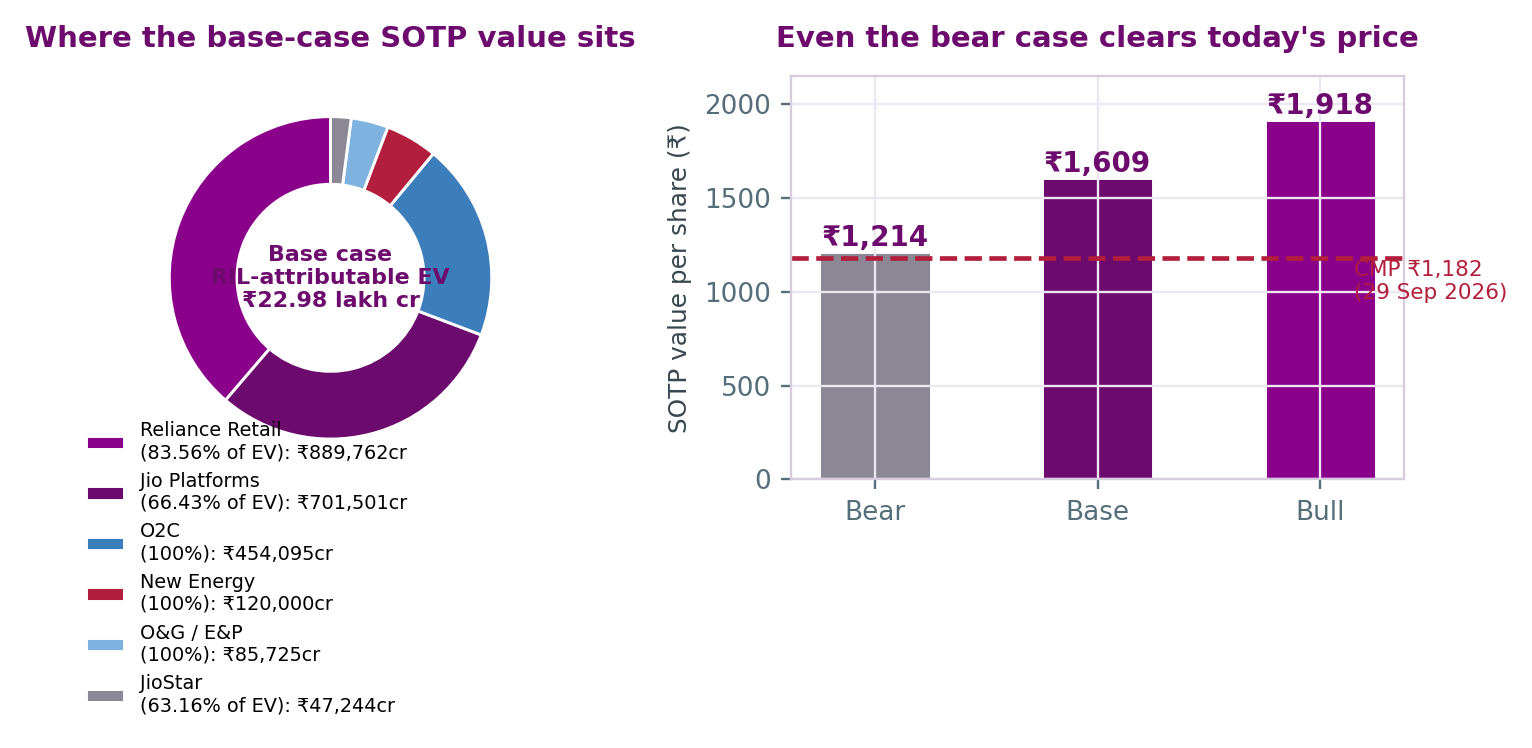
Cross-check (second method): applying a reversion-to-historical-multiple of 11-12x to FY26 consolidated EBITDA of ₹1,79,065 crore (vs. a current blended ~9.6-9.9x per Equirus) and the same net-debt bridge gives an equity value of ₹1,366-1,498 per share (+15.6% to +26.8% upside) — more conservative than our SOTP base case, but independently confirming BUY-territory. The gap between the two methods is itself part of the thesis: a blended consolidated multiple, by construction, cannot separately credit Jio's pending IPO crystallisation or New Energy's optionality the way a segment-level SOTP can — which is precisely the argument for using a SOTP on a conglomerate like RIL in the first place, rather than the single-multiple approach appropriate for the single-business companies elsewhere in Dart Consultants' coverage.
Upgrade triggers: a Jio Platforms IPO listing that prices at or above the $120bn base-case enterprise value; a fresh Reliance Retail valuation mark above the stale $100bn (2023) figure; a disclosed New Energy P&L segment confirming the Equirus-style ₹1.2 lakh crore base case is not overstated. Downgrade triggers: a Jio IPO priced at or below the $92-100bn bear-case range; a further, confirmed retreat in the New Energy/battery strategy beyond the already-disclosed Hithium-to-CATL pivot; explicit evidence of a widening conglomerate discount overriding segment fundamentals, as JPMorgan's own research already flags as a live risk.
| FY24 | FY25 | FY26 | Q1 FY27 | |
|---|---|---|---|---|
| Revenue | — | 9,62,820 | 10,55,780 | 3,40,257 |
| EBITDA | — | — | 1,79,065 | 54,067 |
| Net profit (PAT) | — | 81,309 | 95,754 | 20,946 |
| EPS (₹) | — | 51.47 | 59.69 | — |
| Capex | — | — | ~1,62,000* | 38,682 |
| Net debt | — | — | 1,24,717 | 1,22,914 |
| FY26 PAT is separately reported as ₹80,775cr by Livemint (24 Apr 2026), against Screener.in's ₹95,754cr used above — plausibly a profit-attributable-to-owners vs. total-consolidated-including-minority-interest distinction given RIL's large minority stakes in Jio Platforms and Reliance Retail, but this was not confirmed by any source in our research; both figures are disclosed here per this report's data-honesty standard rather than silently reconciled. FY26 revenue is also cited as "₹11.76 lakh crore" gross (Moneycontrol) and "₹10.8 trillion" (Livemint) — likely gross vs. net-of-excise bases, not reconciled. *FY26 capex is a derived approximation (Q4 FY26 quarterly figure of ₹40,560cr annualised against partial-year data); not a disclosed annual figure. | ||||
| Selected ratios | FY26 / current |
|---|---|
| ROE | ~8.9–11.0% (sources vary) |
| ROCE | ~10.3–12.2% (sources vary) |
| Net debt / EBITDA | 0.57x (30 Jun 2026) |
| Dividend per share (FY26) | ₹6.00 |
| Credit rating | Moody's Baa1 / S&P A- (both upgraded within the last 10 months) |
Balance sheet and cash-flow statements are not reproduced here beyond the net-debt bridge used in the SOTP above; RIL's segment-level capital-employed figures were not accessible via the sources consulted for this report and should be pulled directly from RIL's own investor presentations if required. Source: Screener.in, Tickertape, Moneycontrol, Livemint (all 29-30 Sep 2026 snapshots); RIL's own Q1 FY27 media release dated 17 Jul 2026 for segment operating detail and the net-debt table.
Dart Consultants is a market intelligence and technology service provider, not a SEBI-registered Investment Adviser or Research Analyst. This report is educational material only — not investment advice, and not a recommendation to buy or sell any stock. The BUY rating above is an educational device for summarising public information and one house's own Sum-of-the-Parts construction, not a regulated recommendation. The Sum-of-the-Parts valuation on the preceding page relies on several inputs — most significantly the enterprise value of Jio Platforms and Reliance Retail Ventures, neither of which is separately listed — that are themselves estimates from secondary/brokerage sources rather than directly-observed market prices; readers should treat the resulting target price as one house's first-principles construction, not a certainty, and should independently verify any figure before relying on it. The analyst(s) preparing this report hold no position in, and have no banking, advisory or brokerage relationship with, Reliance Industries Limited, and have received no compensation from the company.
| 12-month target | ₹1,610 |
| CMP (29 Sep 2026) | ₹1,182 |
| Implied upside | +36.2% |
| Rating | BUY |
| Market cap | ₹15,98,344 cr |
| P/E (TTM) | ~19.8–21.4x (sources vary) |
| 52-week range | ₹1,182 – ₹1,612 |
| Book value/share | ~₹668–685 (sources vary) |
| Dividend yield | 0.51% |
| Net debt / EBITDA | 0.57x (30 Jun 2026) |
| Promoter (Ambani family) | ~50.5% |
| FII | ~17.2% |
| DII | ~19.6–21.1% |
| Public | ~11.0% |
| FY25 | FY26 | Q1 FY27 | |
|---|---|---|---|
| Revenue | 9,62,820 | 10,55,780 | 3,40,257 |
| EBITDA | — | 1,79,065 | 54,067 |
| PAT | 81,309 | 95,754* | 20,946* |